Share of Freehold Explained: What to Check Before You Buy (England & Wales)
Share of freehold in England & Wales: how it works, costs, lease extension and reform, common pitfalls, and what to check on the area before you buy.
Share of freehold means you hold your flat on a lease but also jointly own the building's freehold with the other flat owners, giving control over management and usually cheaper lease extensions. Before buying, check the lease length, the freehold structure (trustees or company), filed accounts, current buildings insurance and any unpaid contributions. The arrangement exists only under the leasehold system in England and Wales.
In this guide
- Table of Contents
- At a glance: how share of freehold differs from leasehold and freehold
- How share of freehold works in practice: trustees, nominee purchasers and freehold management companies
- Pros and cons: practical benefits and the common downsides
- How to buy the freehold: collective enfranchisement, informal purchase and alternatives
- Costs, timeline and practical steps to budget for
- Lease extension and mortgage implications for buyers and sellers
- Common pitfalls and how to avoid them
- Tax implications specific to share of freehold ownership
- Governance and decision-making in freehold management companies and trustee arrangements
- Publisher perspective: how a NoFooly area report helps when deciding on a share of freehold
- Which NoFooly report to check before you commit
- Sources
- FAQ
- Recommended

Share of freehold, a feature of the leasehold system in England and Wales, means you own your flat on a lease, as normal, but you and the other flat owners also jointly own the freehold of the building. That gives you a direct say in how the block is run and often makes lease extensions cheaper and simpler, though it also means sharing the admin, the costs and, occasionally, the disagreements that come with running a building together. The rest of this article explains how the ownership is structured, the legal routes to get there, what it tends to cost, and the pitfalls worth planning for.
TL;DR:
- Share of freehold allows flat owners to jointly own the building’s freehold, often reducing costs for lease extensions and increasing management control.
- It is typically held either by personal trustees or a freehold management company, with the latter simplifying future sales and transfer processes.
- The main drawbacks include potential deadlock among owners, administrative responsibilities, and risks of unpaid contributions or lapsed insurance.
- Buying the freehold usually involves valuation, legal fees, and possibly stamp duty, with costs and timeline affected by negotiation and dispute resolution.
- Lenders treat share of freehold flats similarly to leasehold, but owners must ensure lease length, legal documents, and service charges are in order to avoid delays.
Table of Contents
- At a glance: how share of freehold differs from leasehold and freehold
- How share of freehold works in practice: trustees, nominee purchasers and freehold management companies
- Pros and cons: practical benefits and the common downsides
- How to buy the freehold: collective enfranchisement, informal purchase and alternatives
- Costs, timeline and practical steps to budget for
- Lease extension and mortgage implications for buyers and sellers
- Common pitfalls and how to avoid them
- Tax implications specific to share of freehold ownership
- Governance and decision-making in freehold management companies and trustee arrangements
- Publisher perspective: how a NoFooly area report helps when deciding on a share of freehold
- Which NoFooly report to check before you commit
- Sources
- FAQ
At a glance: how share of freehold differs from leasehold and freehold
The three tenures answer the same questions differently: who owns the land, whether a lease sits on top of that ownership, and who is responsible for insurance and service charges.
- Leasehold: you own the flat for a fixed term under a lease; a separate landlord owns the freehold and usually arranges insurance and sets service charges.
- Freehold: you own the building and the land outright with no lease, typical of houses rather than flats.
- Share of freehold: you still hold a lease on your flat, but you and the other leaseholders jointly own the freehold, so you collectively arrange insurance and agree service charges rather than answering to an outside landlord.
Share of freehold applies almost exclusively to flats, because a freehold covering a shared building needs joint ownership to make sense; a single house has no need for it. Buyers often see it as more attractive than pure leasehold, since it removes the layer of a profit-driven third-party landlord and hands decisions back to the people who actually live there, as HomeOwners Alliance notes in its explanation of the arrangement.
How share of freehold works in practice: trustees, nominee purchasers and freehold management companies
Once leaseholders acquire the freehold, someone has to hold the legal title, and there are two common ways to do it.
- Personal trustees: up to four named leaseholders hold the freehold on trust for everyone. It is simple to set up but every sale, remortgage or dispute needs those named individuals to act, which can slow things down as people move away or lose contact.
- Freehold management company (FMC): a company, usually limited by guarantee, holds the freehold instead. Each flat owner becomes a shareholder or member, and the company itself deals with insurance, service charges and repairs.
A nominee purchaser, often that same company, is registered at Companies House and named on the Land Registry title during the enfranchisement process, as described by Lease Advice. A declaration of trust or the company’s articles of association then set out how decisions get made, who can vote, and how liability for the building is shared among owners.
FMCs tend to simplify future sales because the freehold title stays with the company rather than needing every trustee to sign transfer paperwork each time a flat changes hands, a point Lease Advice makes when comparing structures for larger blocks. That is also why lenders and conveyancers generally prefer an FMC over ad hoc trustees once a block has more than a handful of flats.
Pro Tip: If your block has more than four flats, push for a freehold management company rather than personal trustees, since it avoids re-registering ownership every time someone sells.
Pros and cons: practical benefits and the common downsides
The appeal of share of freehold is straightforward, but so are the trade-offs.
- Control over management: you and your co-owners decide who maintains the building, which contractors get used, and how reserves are spent, instead of an external landlord making those calls.
- Cheaper lease extensions: because you are effectively both landlord and tenant, extending your own lease often costs little more than legal paperwork rather than a market premium.
- Influence on service charges: charges are set by agreement among owners rather than imposed, which tends to keep them closer to actual costs.
- Stronger resale appeal: many buyers actively look for share of freehold flats because it removes concerns about an unresponsive or profit-seeking freeholder.
The downsides sit on the other side of the same coin. Running the building means attending meetings, chasing paperwork and sometimes disagreeing with neighbours about spending, and a small group of owners can reach deadlock over a repair bill or an insurance renewal. Non-payment by one flat owner can leave the others covering the shortfall, and compliance duties such as fire safety assessments fall on the owners collectively rather than on a distant landlord who might otherwise carry that burden.
How to buy the freehold: collective enfranchisement, informal purchase and alternatives
There are several routes to share of freehold, and the right one depends on how cooperative the current landlord is and how many leaseholders want in.
- Collective enfranchisement: this is the statutory right for qualifying leaseholders to buy the freehold together, even if the landlord does not want to sell. Lease Advice sets out that leaseholders in a qualifying block use this route via a nominee purchaser, with the price set by a statutory valuation formula that weighs the freehold’s value, the leases’ remaining terms and any marriage value.
- Informal negotiation: some landlords will sell the freehold voluntarily without the statutory process, which can be faster and cheaper in legal fees. There is no obligation on the landlord to agree, though, and a private sale can move to another buyer entirely if leaseholders are not organised.
- Right to Manage: this hands day-to-day management to a leaseholder-controlled company without transferring ownership of the freehold itself. It suits leaseholders who want control over maintenance and service charges but are not ready, or eligible, for a full purchase.
- Acquisition order: a rarer route, available when a landlord persistently fails to meet its management obligations, allowing a court to transfer management or ownership away from them.
The government’s ongoing reform programme, including the Leasehold and Freehold Reform Act 2024, is aimed at making enfranchisement, lease extension and conversion to commonhold easier and fairer, according to the Gov. Buyers weighing up whether to start the statutory process now or wait should keep an eye on how those changes are phased in, since eligibility rules and costs may shift.
Costs, timeline and practical steps to budget for
Buying a share of the freehold is rarely free, and the bill lands before you get the keys to full control.
- Valuation fees for both the leaseholders’ surveyor and the freeholder’s surveyor, since each side typically instructs its own.
- Solicitors’ fees for the leaseholders collectively and often a contribution towards the freeholder’s reasonable legal costs too.
- The freehold purchase price itself, set by negotiation or the statutory formula.
- Stamp duty, where it applies to the purchase, calculated on the price paid for the freehold share.
- Ongoing administration costs once you own the freehold, such as company filing fees for an FMC and annual accounts.
A participation agreement is the single document that protects everyone if things go wrong partway through. It should name the nominee purchaser, cap the maximum price participants will pay, set out how professionals are instructed, and specify what happens if a participant withdraws, according to Lease Advice’s guidance on preparing for enfranchisement. Leaving these terms vague is a common cause of failed or delayed enfranchisements.
Timing and shortfalls matter just as much as the price you eventually pay. Valuation and negotiation typically take several months, and disputes over price can end up in front of the First-tier Tribunal if the parties cannot agree, adding further delay. If a participant drops out midway, the remaining leaseholders need a plan for covering the gap, which is exactly what a participation agreement is meant to pre-empt.
Lease extension and mortgage implications for buyers and sellers
Lease length affects mortgageability long before it affects your own comfort living there. Lenders commonly grow cautious once a lease drops below around 80 years remaining, because the value of a short lease erodes faster as it approaches zero.
- Owning a share of the freehold often makes extending your own lease to a very long term straightforward and cheap, since you are agreeing terms with yourself rather than negotiating against an external landlord.
- That said, extension is not automatic. Company or trust decisions still need the other owners’ agreement, and paperwork has to be updated at the Land Registry.
- Reforms under the Leasehold and Freehold Reform Act are intended to make statutory lease extensions cheaper and easier across the board, which will affect both share-of-freehold owners and those still under an external landlord.
- When selling or remortgaging, lenders will typically want to see the remaining lease term, evidence of the freehold structure (trust deed or company details), and confirmation that service charges and insurance are up to date.
Keeping those documents organised in advance, rather than scrambling for them once a sale is agreed, avoids a large share of the delays that hold up completions on share-of-freehold flats.
Common pitfalls and how to avoid them
Most share-of-freehold problems trace back to paperwork that was never tidied up rather than anything more dramatic.
- Missing governance documents: a participation agreement that was never finalised, or FMC filings that have lapsed at Companies House, both create confusion when it matters most.
- Lapsed building insurance: if nobody is clearly responsible for renewing the policy, cover can expire without anyone noticing until a claim is needed.
- Non-payment of contributions: one owner falling behind on service charges can leave the rest to cover the shortfall or start a formal dispute process.
Practical pitfalls such as unpaid contributions, lapsed cover and missing filings are recurring causes of costly delays, according to specialist legal guidance on lease extensions and freehold risks. The fix is unglamorous but effective: keep the participation agreement, insurance schedule and company filings current, and bring in a solicitor or managing agent early rather than after a dispute has already started.
Pro Tip: Ask to see the FMC’s last three years of filed accounts and confirmation of current buildings insurance before you commit to buying into a share-of-freehold flat.
Tax implications specific to share of freehold ownership
Buying into a share of freehold does not create a separate tax regime of its own, but it does add a few wrinkles worth understanding before you sign anything.
Stamp duty is charged on the price you pay to acquire your share of the freehold, in the same way it applies to any other property purchase, so the purchase price agreed through enfranchisement or informal negotiation is the figure that matters for that calculation. If the freehold is held through an FMC and you hold shares in that company rather than the land directly, those shares generally have no separate market value beyond your flat, since the articles usually tie them to the ownership of a specific flat rather than allowing them to be traded independently.
Service charges and ground rent collected by the FMC are generally not treated as income to the individual owners, since the company is holding and spending the money on behalf of the building rather than distributing a profit. If the freehold generates income beyond service charges, such as from letting a communal space, that income may have tax consequences for the company or the owners, and this is a point worth raising with an accountant rather than assuming either way.
None of this amounts to tax advice, and the right treatment depends on how your particular freehold is structured. A solicitor or accountant familiar with enfranchisement should confirm the position for your specific purchase.

Governance and decision-making in freehold management companies and trustee arrangements
However the freehold is held, decisions still have to get made, and the mechanism differs depending on the structure.
In a freehold management company, the articles of association typically set out voting rights, usually one vote per flat or per share, and specify what needs a simple majority against what needs a larger threshold, such as a special resolution for major works or a change to the company’s rules. Directors, often drawn from the flat owners themselves, handle day-to-day matters like arranging insurance renewal or instructing a managing agent, while bigger decisions go to a general meeting of all members.
Where personal trustees hold the freehold instead, decisions are usually governed by a declaration of trust rather than company articles. That document should set out how the trustees must act, for instance requiring unanimous agreement or a majority among the named trustees, and what happens if a trustee dies, sells their flat or becomes unreachable. Because trustees are individuals rather than a company, replacing one who has moved away can be more cumbersome than simply transferring shares in an FMC.
In both structures, disputes that cannot be resolved internally can end up before the First-tier Tribunal or, in serious cases, the county court, which is one more reason a clear governance document drafted at the outset is worth the legal fee at the time.

Publisher perspective: how a NoFooly area report helps when deciding on a share of freehold
Share of freehold tells you about the building’s legal structure, but it says nothing about whether the street, the flood history or the school catchment around it stack up. That is a separate piece of homework, and it is easy to skip when you are focused on lease terms and trustee agreements.
For a straightforward look at the local risks and resale context, the £9 Instant Report from NoFooly covers sold prices by street and type, flood detail, crime and planning applications nearby. For a specific decision on a share-of-freehold flat, the person-checked Area Report (from £19) goes further: a named analyst checks it against your own brief, adds the property's sale history and tenure, and gives a plain-English verdict with an indicative read of whether the asking price looks fair against local evidence. It is not a survey and does not read legal title or building condition, and it covers England & Wales only.
Which NoFooly report to check before you commit
Choosing between share of freehold flats often means comparing more than one street or block, and that is exactly where a person-checked report earns its keep rather than a stack of listing portals and forum threads.
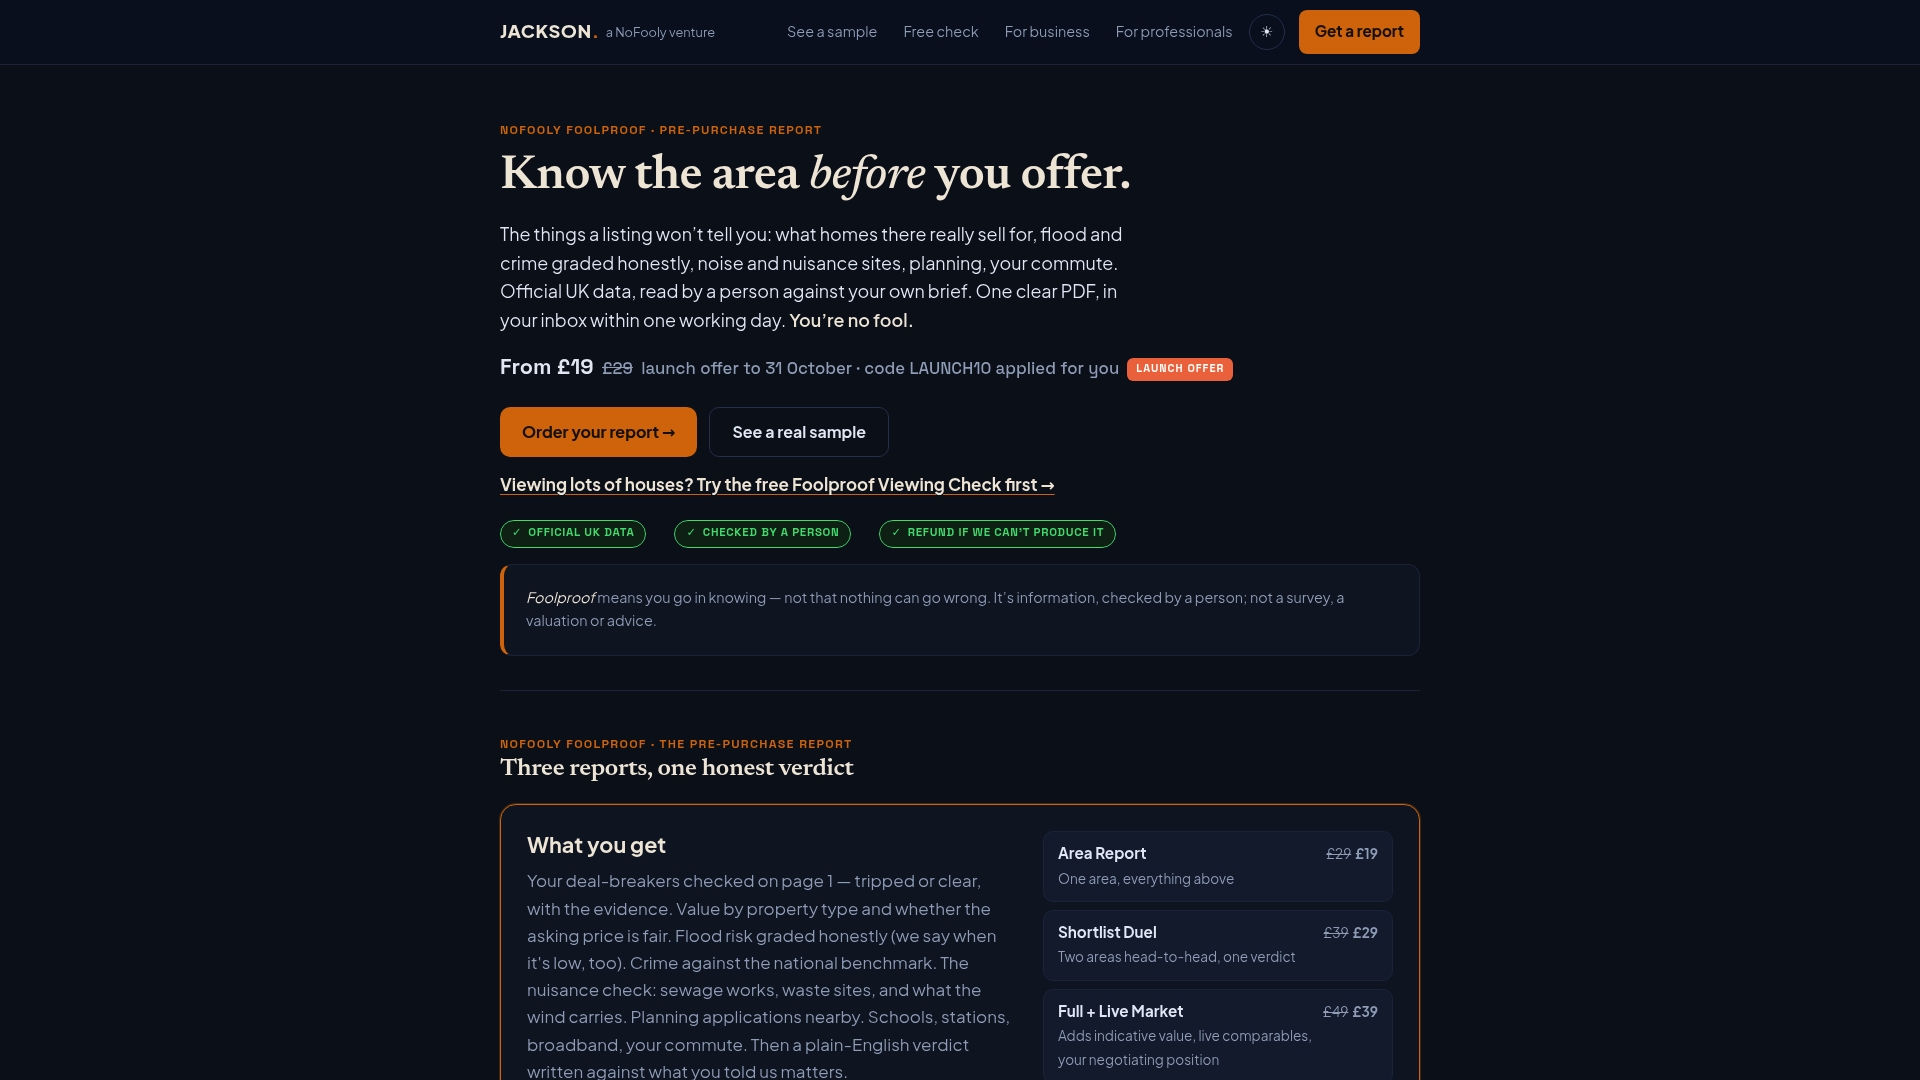
For a single flat you are seriously considering, an Area Report gives you a named analyst's indicative read on the asking price, the sale history and the commute, checked against your own deal-breakers. If you are torn between two buildings or two streets, a Shortlist Duel puts them head to head. Buyers who want live comparables and an indicative, orientation-only price estimate alongside rental yield data can step up to a Full + Live Market report.
| Product | Price | Best for |
|---|---|---|
| Instant Report | £9 | A first automated check on flood, crime, planning and sold prices |
| Area Report | from £19 | A named verdict on one specific flat against your brief |
| Shortlist Duel | see site for current price | Comparing two areas or buildings head to head |
| Full + Live Market | see site for current price | Live comparables plus an indicative, orientation-only price estimate and yield |
Every report is data, not advice, and none of them is a survey, a conveyancer or a mortgage valuation. Start with a postcode at NoFooly: the Instant Report arrives in minutes and the person-checked Area Report within one working day.
Sources
For the official position on leasehold reform, see the Leasehold toolkit on gov.uk and the draft Commonhold and Leasehold Reform Bill explanatory notes. For practical steps on buying a freehold together, Lease Advice is a reliable starting point.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
Is it worth buying a share of freehold?
For most flat owners, yes: it usually gives you more control over management and cheaper lease extensions than staying under an external landlord. The trade-off is shared responsibility for costs and decisions, so it suits owners willing to engage with running the building rather than leaving everything to a landlord.
Is it harder to get a mortgage with a share of freehold?
No, lenders generally treat share of freehold flats the same as any other leasehold flat, provided the lease itself has enough years remaining and the paperwork is in order. What can slow things down is a lender wanting to see the trust deed or company details and confirmation that service charges and insurance are current, as outlined in guidance from Lease Advice.
What does share of freehold mean in England and Wales?
It means you own your flat under a lease, exactly as any leaseholder does, but you also jointly own the freehold of the building with the other flat owners. According to HomeOwners Alliance, this means you share responsibility for insurance and management rather than answering to a separate landlord.
What are the disadvantages of share of freehold?
The main downsides are administrative: attending meetings, chasing paperwork, and occasionally disagreeing with co-owners over spending or repairs. There is also a risk that one owner falls behind on payments, leaving the others to cover the shortfall, and compliance duties such as fire safety fall on the group rather than an outside landlord.
— Gracie C
Recommended
Short on time? Let us run the checks for you
Viewing this weekend and don't fancy an afternoon of maps? The free Foolproof Viewing Check pulls the headline tiles for any address you're looking at — no card, no sign-up.
Want the whole area read by hand and written up, checked and signed off by a real person before it reaches you? That's the Jackson pre-purchase area report. Software does the legwork so it's quick and affordable; a person makes the call so you can trust it. Reports start from £19.